Nov 4, 2026 · @Michael Oeth
I’ve seen this movie before. From 2004 to 2020 I ran OnSIP, a hosted VoIP company, and I watched the whole VoIP industry boom, shake out and consolidate around me.
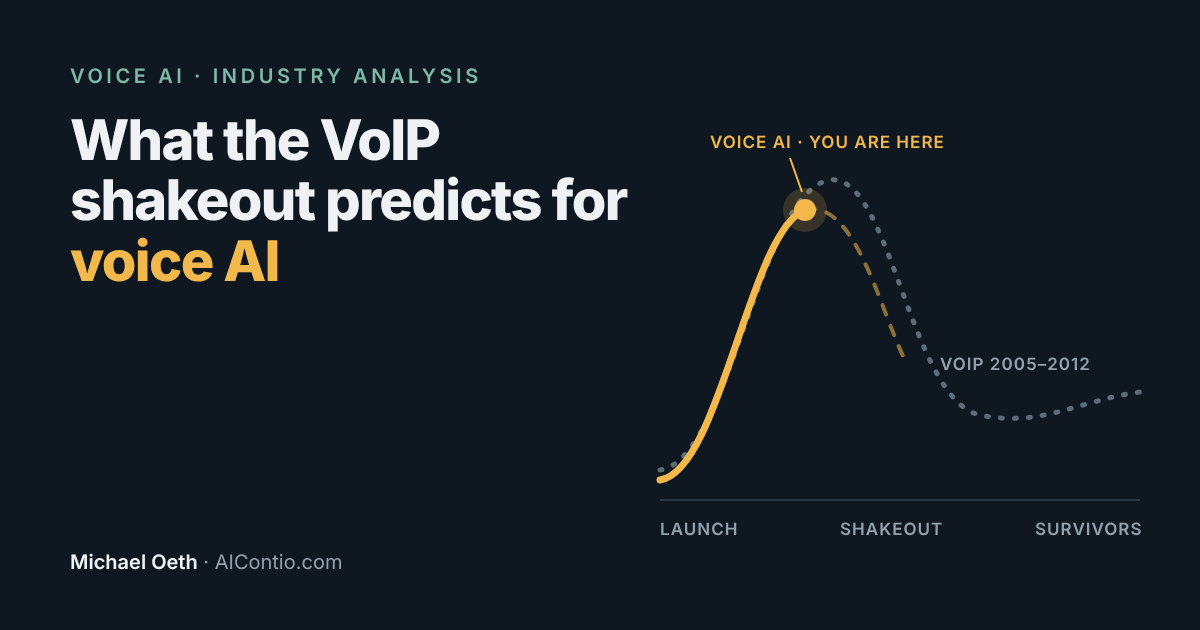
Voice AI is about two years into the same cycle. The technology works. Hundreds of companies are launching, raising money and selling nearly identical products. Most of them won’t be here in three years, and it won’t be because their AI wasn’t good enough.
Here’s what the VoIP shakeout taught me, and what I think it predicts for voice AI.
What the VoIP shakeout looked like
In the mid-2000s, VoIP was the hot category. Calls over the internet cost a fraction of a phone line, and anyone with a SIP server and a credit card processor could become a phone company. Hundreds did.
Then the market sorted itself out, fast:
- Vonage, the category leader, went public in May 2006 at $17 a share with about 1.6 million subscribers. It closed its first day at $14.85, the worst first-day drop of any IPO that year. (Spokesman-Review)
- SunRocket, the No. 2 stand-alone VoIP provider, shut down without warning in July 2007. More than 200,000 customers lost service, many of them on plans they had prepaid for a year. (Washington Times)
- Comcast, which had no VoIP heritage at all, became the third-largest residential phone provider in the US by 2009, with about 6.5 million Digital Voice customers. (Comcast)
The companies with the best technology didn’t automatically win. The ones with distribution, staying power and customer trust did.
Lesson 1: The core product goes to zero
Early VoIP companies sold cheaper minutes. Within a few years, minutes weren’t a product anymore. “Unlimited calling” became the default, and then it became a feature of something else.
At OnSIP, we only charged extra when a call touched the public phone network. Calls between users were free. That model worked because we never pretended minutes were where the value was.
Voice AI is on the same path. Most platforms price per minute today, and most of that minute is a markup on tokens, speech-to-text and text-to-speech. All three are getting cheaper every quarter. If your margin is the gap between what you pay the model providers and what you charge per minute, you’re selling minutes. That gap is going to close.
What survives: pricing tied to outcomes the customer cares about, like booked appointments, qualified leads or calls resolved without a human.
Lesson 2: Distribution beat technology
Comcast wasn’t the most innovative VoIP provider. It didn’t need to be. It already had the customer, the truck roll and the monthly bill. Adding a phone line was one more line item, and millions of households said yes.
The same thing is about to happen in voice AI. RingCentral, Zoom, 8×8, the carriers and every hosted PBX provider already own the phone numbers and the bill. When they add an “AI receptionist” checkbox, many small businesses will choose it over a better product from a startup, because it’s one less vendor and one less integration.
What survives: startups that either sell through those providers or solve a problem the bundled version can’t, such as a specific industry’s workflows, compliance and edge cases.
Lesson 3: Shutdowns hurt customers more than bad features
When SunRocket went dark, its customer service line played a recording saying it was no longer taking calls. Customers who had prepaid for a year were left scrambling to port their numbers to someone else, a process that could take weeks. A bad feature is an annoyance. A provider that disappears takes your phone number with it.
Voice AI has the same exposure, plus some new ones. When a voice AI startup folds, ask:
- Who controls the phone numbers your customers call?
- Can you export your prompts, call flows and function definitions, or are they locked in a proprietary builder?
- Where are your call recordings and transcripts, and can you get them out?
- What happens to the calls coming in the morning after?
What survives: platforms that make leaving easy enough that customers trust them to stay. Buyers should ask these questions before signing, not after.
Lesson 4: The providers behind the providers did well
BroadSoft almost never sold to an end customer. It sold the platform that service providers used to run hosted voice. By the time Cisco agreed to buy it for about $1.9 billion in 2017, BroadSoft was used by 25 of the world’s top 30 service providers by revenue, in 80 countries. (Cisco)
White-label voice AI platforms are making the same bet: let the resellers, MSPs and telecom providers own the customer, and be the engine underneath all of them. My recent Behind the Call on UponAI looked at exactly this model.
There’s a catch. BroadSoft won because its platform was carrier-grade. Service providers could put their name on it without worrying it would embarrass them. In voice AI, that means safe defaults: agents that don’t claim bookings that never happened or book appointments for callers with chest pain.
What survives: platforms resellers can put their name on without needing an expert prompt engineer on every account.
Lesson 5: The survivors owned the customer relationship
At OnSIP, I answered support calls myself, regularly, as CEO. My team called it “Undercover Boss, every day.” It wasn’t a stunt. It was how I learned where the product actually broke, and it was a big part of why customers stayed when cheaper options showed up every month.
Support was one of our biggest advantages at OnSIP. Our customer attrition was among the lowest in the industry. That’s not a soft metric. If you spend money to acquire a customer and then lose them within a year because of lousy support, you never make back your investment.
Voice AI companies have a version of this problem that’s easy to miss. The agent is the customer relationship. Every call it handles is your company talking to your customer’s customer. If it confidently says “you’re all set” when nothing was booked, you lose trust twice: with the caller and with the business that bought your product.
What survives: companies that treat every call as a support interaction they’re accountable for, and can prove what the agent actually did.
Where the analogy breaks
The parallel isn’t perfect, and the differences matter:
- The shakeout will be faster. VoIP took most of a decade to consolidate. Model capabilities and costs change every few months now, so a product advantage can disappear in one release cycle.
- The failure mode is different. A bad VoIP provider dropped calls or had outages, and everyone noticed. A bad voice AI agent completes the call, sounds great and quietly gets it wrong. Nobody notices until the customer doesn’t show up for the appointment they were told was booked.
- The underlying models aren’t yours. VoIP providers could own their switching and network. Most voice AI companies rent the same handful of models, voices and telephony providers, so much of the product is shared by everyone in the category.
- Telecom still matters. Transfers, SIP, DTMF, caller ID, voicemail detection and number porting didn’t go away. Plenty of AI-native companies are relearning lessons VoIP learned 20 years ago.
My prediction
By 2029, most of today’s voice AI companies will have been acquired, bundled into something bigger or shut down. The ones left standing will own one of two things: distribution or trust.
If you’re building:
- Don’t build a business on per-minute markup. Price on outcomes.
- Pick your channel now. Either sell through the providers who own the customer, or own a vertical so deeply the bundled AI can’t follow you.
- Make it easy for customers to leave. Exportable prompts, portable numbers and accessible logs build the trust that makes them stay.
- Verify what your agent claims it did. That’s the difference between a demo and a product.
If you’re buying:
- Ask who owns your phone numbers, prompts and call data, and how you get them out.
- Ask how the platform checks that a booking or transfer actually happened.
- Ask what happens to your calls if the company shuts down tomorrow. SunRocket’s customers wish they had.
VoIP didn’t fail. It won so completely that it became invisible, just how phones work. Voice AI will probably go the same way. The open question is which companies will still be standing when it does.
If you lived through the VoIP shakeout too, I’d like to hear what you think voice AI builders are about to learn the hard way.
Sources
- Vonage shares fall in debut, Spokesman-Review, May 2006
- VoIP provider closes abruptly, Washington Times, July 2007
- Comcast now the third-largest residential phone services provider, Comcast, March 2009
- Cisco announces agreement to acquire BroadSoft, Cisco, October 2017